
When you work in the healthcare field and lives are literally on the line, you must take numerous extra precautions to protect yourself and your career. One such action involves getting set up with the right coverage in case of a disaster. That means finding adequate medical malpractice insurance, also known as doctor's liability insurance.
Fortunately, an independent insurance agent can help you get set up with the right kind of medical professional liability insurance for your needs. Better yet, they’ll get you equipped with the proper coverage long before you ever need to actually use it. But first, here's a closer look at this crucial protection.
Key Takeaways - Medical Malpractice Insurance: 2026
Medical malpractice insurance is a specialized form of professional liability insurance that covers the cost of claims arising from alleged professional errors and negligence.
Seven states require medical malpractice insurance by law: CO, CT, KS, MA, NJ, RI, WI.
The average cost of medical malpractice insurance is $7,500 per year, but premium rates vary by specialty, location, and other factors.
Working with a local independent insurance agent is strongly recommended, as they can shop and compare medical malpractice insurance quotes from multiple carriers near you to find the best rate and fit for your specialty.
What Is Medical Malpractice Insurance?
Doctor's liability insurance, also called medical malpractice insurance, is a type of coverage designed for professionals who work in the medical field, including various types of healthcare providers such as physicians, dentists, pharmacists, psychologists, and more. This coverage is critical for medical professionals to guard against lawsuits for negligence resulting in accidental injuries or death.
Medical malpractice insurance is essentially a form of professional liability insurance designed to protect healthcare professionals against lawsuits relating to professional errors. Doctors and other medical professionals rely on this coverage to protect their practices from extremely costly lawsuits that could otherwise lead to bankruptcy. In fact, the average malpractice settlement in the U.S. ranges from $242,000 to $348,065. An independent insurance agent can help you and your practice get equipped with the necessary doctor liability insurance for your field.
What Does Medical Malpractice Insurance Cover?
Medical professional liability insurance is a special form of professional liability insurance designed to protect professionals in the medical field. This coverage protects medical professionals from the legal expenses required to defend and settle medical malpractice lawsuits, as well as settlement fees if they are found to be liable for the claim.
Medical malpractice insurance usually covers the following:
- Costs of medical damages
- Costs of punitive and compensatory damages
- Costs of arbitration and settlement
- Costs of attorney and court fees (defense costs)
- Costs of alleged HIPAA data breaches
- HIPAA violation fines
You may need to add cyber liability insurance coverage to your medical malpractice policy to have the right coverage against HIPAA data breaches. Your independent insurance agent can further explain the critical protections provided by medical malpractice insurance and why you need it.
Claims-Made vs. Occurrence: Understanding Your Policy Options
Doctor's liability or medical malpractice insurance comes in three basic forms. It's important to get your practice equipped with the type that works best for you.
- Claims-made medical malpractice insurance: This coverage only reimburses the policyholder if the service is provided and the claim is made while the policy is in force. However, some policies include "tail" coverage, which extends protection for a specified amount of time, such as five years, after the policy's end date. Tail coverage is beneficial for healthcare workers who are retiring, switching positions, or changing insurance policies.
- Occurrence medical malpractice insurance: This coverage reimburses the policyholder if the service is provided while the policy is in force, regardless of when the claim is filed. Tail coverage is not required for occurrence policies.
You might also be able to add nose coverage to a claims-made policy with a retroactive coverage date set before your policy's term began. Setting a retroactive date in a claims-made policy provides you with protection for incidents that occurred in the past.
Tail coverage extends a policy's protection after its term ends. Retiring physicians often purchase tail coverage to protect themselves even after they're no longer working. Tail coverage malpractice insurance costs an average of 1.5-2 times your expiring malpractice insurance's premium. An independent insurance agent can help you determine which type of medical malpractice insurance makes the most sense for you.
What Doesn't Medical Malpractice Insurance Cover?
Doctor's liability insurance unquestionably provides critical coverage for medical professionals, but it doesn’t cover everything. Coverage also comes with its own set of exclusions, which often include the following:
- Criminal acts
- Inappropriate alteration of medical records
- Intentional and dishonest acts
- Sexual misconduct liability
- Punitive damage (excluded by certain policies depending on state laws)
An independent insurance agent can help address any concerns you may have about what your doctor's liability insurance policy excludes.
Top Medical Malpractice Insurance Carriers for 2026
Many different carriers underwrite medical malpractice insurance policies. Here are just a few of our top recommendations for the best medical malpractice insurance carriers of 2026.
| Carrier | Qualifier |
|---|---|
| DocShield | Best for orthopedic surgeons |
| The Doctors Company | Best for physician-focused coverage |
| MedPro Group | Best for financial strength |
| Coverys | Best for physician risk management and claims protection |
| CNA | Best for name-brand coverage |
An independent insurance agent can help you determine if the doctor's liability coverage provided by any of these leading insurance carriers is right for you.
Options for Purchasing Doctor's Liability Insurance
When shopping for physician liability coverage, you often have a few different options, including the following.
- Policies held by an employer, like a hospital
- Policies from a traditional private insurer, either individual or group coverage
- Policies offered through a medical risk retention group (i.e., a member-owned, healthcare-specific medical professionals organization that provides doctor's liability coverage, typically at a lower cost)
Doctors and other medical professionals don't need medical malpractice insurance if they work for the Federal government, which is already self-insured against lawsuits. However, other medical professionals need to find enough coverage for themselves as employees, for their practice, and for their employees, if applicable. An independent insurance agent can also help you find the right physician liability coverage.

Common Medical Malpractice Insurance Claims
There are numerous reasons doctors and other medical professionals are sued regularly. A doctor might prescribe a medication that makes a patient ill, who, in turn, decides to press charges. Remember that the average malpractice settlement in the U.S. can reach up to $348,065, which makes having the right coverage critical. The hefty cost of the average settlement can also justify any malpractice insurance premiums.
Wrongful diagnosis is another common claim against doctors. Whether you're actually found guilty or not, it's imperative to have enough coverage for yourself and your practice before a lawsuit ever arises. Here are some of the most common medical malpractice insurance claims:
- Surgical errors, such as wrongful site or unnecessary surgery
- Failure to diagnose
- Misdiagnosis
- Medication or dosage errors
- Premature discharge
- Aftercare and follow-up errors
- Laboratory result errors
- Failure to evaluate patient history
Most common doctor's liability insurance claims
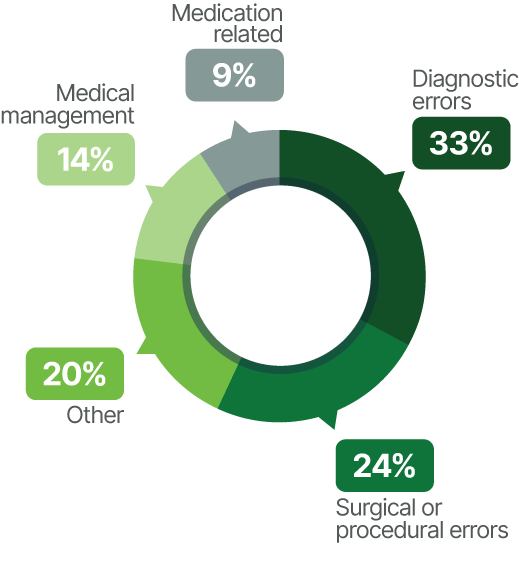
Diagnostic errors account for one-third of all doctor's liability claims. Surgical and procedural errors account for one-fourth. Fortunately, doctor's liability insurance can protect you against lawsuits relating to any of these disasters, and more.
Who Needs Medical Malpractice Insurance?
Anyone in the medical field who treats patients should have physician liability coverage. This crucial coverage is needed by the following professionals:
- Physicians, specialists, and surgeons
- Physician assistants
- Dentists
- Anesthesiologists
- Nurses and nurse practitioners
- Psychiatrists
- Gynecologists
- Obstetricians
- Physical therapists
- Optometrists
- Chiropractors
- Nursing students
- Pharmacists
- Podiatrists
Assistants to any of these professionals also need medical malpractice insurance. An independent insurance agent can help insure your whole team with the right coverage, including malpractice insurance for nurses and nurse practitioners or malpractice insurance for small medical practices.
How Much Does Medical Malpractice Insurance Cost in 2026?
On average, medical malpractice insurance costs $7,500 per year. However, malpractice insurance premiums often range from $4,000 to $12,000 per year for many medical professionals. The cost of physician liability coverage rose by 68% of medical groups in 2024 compared to 2022, according to an MGMA poll.
Overall, coverage costs for doctor's liability insurance can vary greatly, depending on your profession and more. Here are some of the key factors that go into your policy's premium.
- Your professional specialty (e.g., doctor, psychiatrist, etc.)
- How many years of experience you have
- If you work full-time, part-time, etc.
- Your claims history, or any outstanding claims
Many medical professionals pay between $4,000 to $12,000 annually for their coverage. Surgeons, however, pay quite a bit more, often up to $50,000 annually.
Typically, healthcare professionals spend about 3.2% of their annual income on medical malpractice insurance. An independent insurance agent can find exact medical malpractice insurance quotes for your area.
Medical Malpractice Insurance Cost by Specialty
In general, malpractice insurance for surgeons costs more than coverage for physicians. The average OB-GYN malpractice insurance annual premium ranges from $14.6K in California to nearly $66.4K in Florida. The table below compares the average cost of medical malpractice insurance by specialty for 2026.
| State | Internal Medicine Average Annual Premium | General Surgery Average Annual Premium | Obstetrics/Gynecology Average Annual Premium |
|---|---|---|---|
| California | $8,784 | $15,284 | $14,616 |
| New York | $5,220 | $22,541 | $28,212 |
| Florida | $15,436 | $49,942 | $66,373 |
| Illinois | $12,175 | $37,455 | $54,307 |
| North Dakota | $4,273 | $13,851 | $18,200 |
| Wisconsin | $3,261 | $9,781 | $14,945 |
An independent insurance agent can help you compare rates for physician liability insurance by specialty, including malpractice insurance for nurses and nurse practitioners.
Medical Malpractice Insurance Rates by State
Medical malpractice insurance rates by state vary widely. Some of the highest-cost states for this coverage include New York, Florida, and Illinois, while the lowest-cost states include North Dakota, Wisconsin, and California. For example, the average cost of malpractice insurance for an internal medicine practitioner in Florida averages $15,436 per year, while the same coverage costs just $3,261 per year in Wisconsin.
Is Medical Malpractice Insurance Required in Your State?
Medical malpractice insurance is not federally required, but seven states do require various professionals to have coverage. Medical professionals are required to have professional liability insurance in the following states:
- Colorado
- Connecticut
- Kansas
- Massachusetts
- New Jersey
- Rhode Island
- Wisconsin
Additionally, seven states require doctors to have a minimum level of coverage to participate in state programs that provide supplemental malpractice coverage or limit the amount of damages from a malpractice claim. These states include:
- Indiana
- Louisiana
- Nebraska
- New Mexico
- New York
- Pennsylvania
- Wyoming
California requires malpractice coverage for professionals who perform outpatient surgery only. Florida also has unique coverage exemption rules. Be sure to ask a local independent insurance agent, "Is medical malpractice insurance required in my area?"
Some medical professionals opt to "go bare," meaning not to have coverage, because they believe they will be less of a target to get sued. Other professionals opt to go without coverage because of the high costs of the premiums. Regardless of whether coverage is required, it's critical for your practice to have this protection.
How Do Medical Malpractice Insurance Limits Work?
The limits provided in your doctor's liability insurance work similarly to those included in your car insurance. Doctor's liability insurance limits often look like this: $1 million/$3 million.
- The $1 million is the maximum amount your insurance will pay out per claim.
- The $3 million is the maximum amount of coverage provided by your insurance every year.
So, if you had three claims that all needed $1 million payouts, you'd have exhausted all of your medical malpractice coverage for that year. However, surgical specialties and hospital-affiliated physicians often need policies with $5M/$10M coverage limits as a credentialing condition. An independent insurance agent can help you get set up with all the physician liability coverage you need to comply with hospital credentialing malpractice insurance requirements.
HIPAA Compliance and Cyber Risks for Healthcare Professionals
Standard medical malpractice insurance policies typically exclude coverage for HIPAA fines and cyber-related claims. That's why having a separate cyber liability insurance policy is highly recommended to protect against the cost of data breaches, cyberattacks, and other digital threats. Be sure to ask an independent insurance agent to help you add HIPAA violation coverage insurance to your medical malpractice policy.
FAQs About Medical Malpractice Insurance
Are doctors required to get their own liability insurance?
Only seven states require doctors to have liability insurance by law: CO, CT, KS, MA, NJ, RI, and WI. However, having coverage is crucial to protect yourself and your practice and employees against costly professional errors. Required coverage limits range from $100,000-$1M per occurrence and $300,000-$3M aggregate. If you're still asking, "Is medical malpractice insurance required in my state?", a local independent insurance agent can help confirm your coverage requirements.
Can a doctor practice without malpractice insurance?
Technically, if you work in a state where medical malpractice insurance is not required by law, you could practice without this coverage. But the doctor would be risking their entire business operation without the right doctor's liability insurance. The average malpractice settlement in the U.S. costs up to $348,065, which makes having this coverage essential.
How much does medical malpractice insurance cost per year?
Many medical professionals pay between $4,000 to $12,000 annually for their coverage. Family physicians pay an average of $5,000 to $15,000 per year, surgeons pay $30,000 to $50,000 per year, and OB-GYNs pay up to $226,224 per year in high-litigation states. Still asking, "How much does medical malpractice insurance cost?" An independent insurance agent can find exact medical malpractice insurance quotes for your area.
What kinds of doctors need liability insurance?
Physicians, specialists, surgeons, dentists, anesthesiologists, nurses and nurse practitioners, and psychiatrists all need doctor's liability insurance. Allied health professionals, such as physical therapists, chiropractors, and optometrists, also need coverage. These medical professionals' assistants all need their own malpractice insurance, as well.
Is there a difference between medical malpractice and doctor's liability insurance?
No, these two terms are often used interchangeably. Doctor's liability insurance is the same thing as medical malpractice insurance.
How much medical malpractice insurance do you need?
You need enough doctor's liability insurance to protect you against any possible lawsuits that may arise within the coverage period. Coverage limits of $1M/$3M are standard. However, hospitals often require higher limits as a credentialing condition, and surgical specialties may need $5M or more in coverage. An independent insurance agent can help you determine the right amount of coverage you need.
If my company pays for my doctor's liability coverage, how do I know if I have enough?
You'll need to ask to review your company's policy, and also consult an independent insurance agent. It's always a safe idea to have more coverage from the very beginning. Additionally, employer policies are typically claims-made, meaning the physician may not be covered if they leave the practice without securing tail coverage first.
What other legal risks do healthcare professionals face beyond malpractice?
In addition to negligence claims, doctors and other healthcare professionals can face lawsuits due to cyber and regulatory risks. Healthcare professionals must comply with the Health Insurance Portability and Accountability Act (HIPAA). Those who work in the medical field may also want to consider getting cyber liability insurance to protect themselves against the cost of lawsuits related to data breaches and other cyber risks. Further, healthcare professionals often face wage/hour claims, HIPAA violation penalties, and board licensing complaints.
What is tail coverage and how much does it cost?
Tail coverage extends a claims-made policy after it ends. Tail coverage malpractice insurance costs roughly 1.5x-2x the expiring policy's final annual premium as a one-time fee. This coverage is essential for physicians retiring, switching jobs, or changing carriers.
Why Work with an Independent Insurance Agent for Medical Malpractice Coverage?
When it comes to helping insurance customers find the absolute best medical malpractice coverage, no one’s better equipped to help than an independent insurance agent. Wondering how to compare malpractice insurance quotes? Independent insurance agents search through multiple carriers to find providers who sell doctor's liability insurance, deliver quotes from a number of different sources, and help you walk through them all to find the best blend of coverage and cost.
These agents can access specialty medical malpractice insurance markets, including risk retention groups and surplus lines carriers. These channels are unavailable from direct writers. And down the road, your independent insurance agent can help you file medical malpractice insurance claims or update your coverage as necessary.
Sources
https://www.iii.org/article/understanding-medical-malpractice-insurance
https://www.sermo.com/resources/how-much-does-malpractice-insurance-cost/
https://medpli.com/occurrence-vs-claims-made-malpractice-insurance-whats-the-difference/
https://physiciansthrive.com/malpractice-insurance/costs/
https://stromlaw.com/how-much-is-the-average-medical-malpractice-settlement/
https://doctiplus.net/top-malpractice-insurance-carriers-and-platforms-for-orthopedic-surgeons-in-2026/
https://www.insureon.com/small-business-insurance/medical-malpractice/state-laws